


Financial technology, widely known as FinTech, is changing how people save, borrow, transfer, invest, and manage money. By combining financial services with software, mobile connectivity, data analytics, and automation, FinTech companies are developing new ways to deliver financial products. The result is an increasingly digital financial environment in which convenience, speed, and accessibility are becoming important competitive advantages.
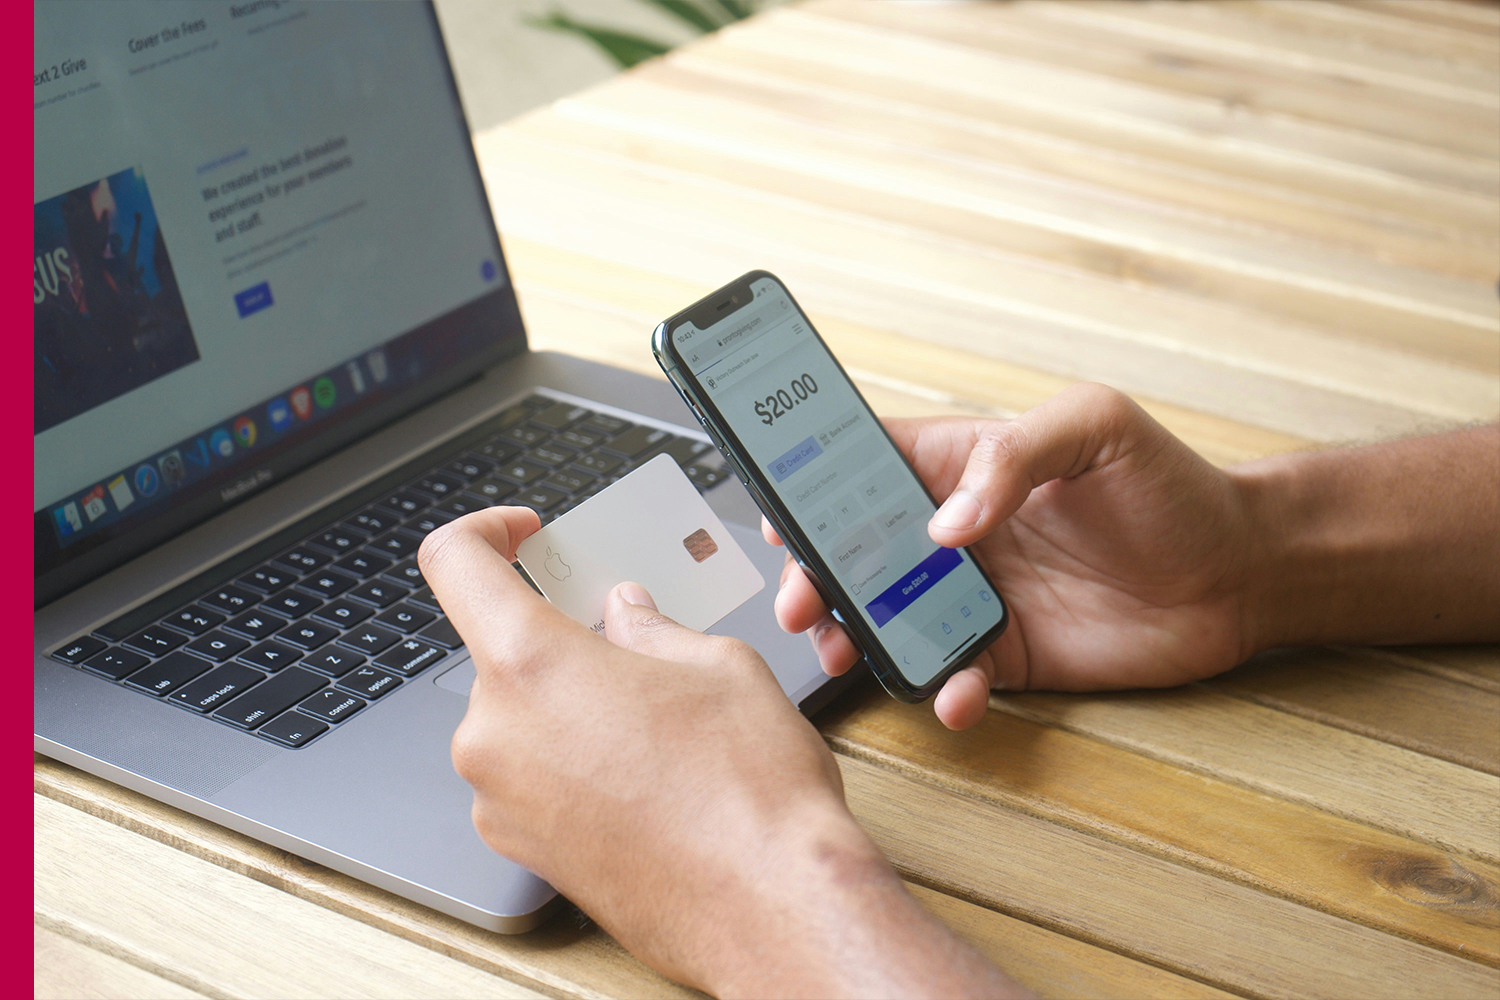
Digital payments are among the most visible examples of this transformation. Mobile applications, digital wallets, contactless payments, and instant payment systems allow users to complete many transactions without handling physical cash. In India, the expansion of the Unified Payments Interface has helped make real-time digital payments part of everyday life for consumers and businesses. Small retailers, independent professionals, and online sellers can receive payments through digital channels that were once more difficult to access.
Another important development is the digitisation of lending. Some financial platforms use digital applications and alternative data to support credit assessments and streamline parts of the loan process. This may help certain customers access credit more efficiently. However, digital lending also creates risks involving hidden charges, excessive borrowing, misuse of personal information, and unclear recovery practices. Transparent terms, responsible underwriting, and effective consumer protection are essential.
Artificial intelligence is becoming increasingly important in financial services. AI-based systems can help identify suspicious transactions, support customer-service interactions, analyse spending patterns, and assist institutions in assessing risk. Automated tools may also help businesses categorise expenses or forecast cash flow. However, these systems must be monitored carefully because inaccurate data and biased models can affect the quality and fairness of financial decisions.
Personal finance applications are another growing area. Some tools help users track spending, establish savings goals, receive payment reminders, or organise financial information. By making spending patterns more visible, these platforms may encourage better financial habits. Their value depends on usability, accuracy, privacy protections, and the extent to which they help users make informed choices rather than simply encouraging additional transactions.
FinTech is also creating new opportunities for small businesses. Digital invoicing, online payment collection, accounting software, and integrated financial platforms can simplify administrative work. When systems connect sales, expenses, inventory, and payments, business owners may gain a clearer picture of their financial position. This can support more timely decisions, particularly for enterprises operating with limited resources.
Despite these advantages, the expansion of digital finance increases the importance of cybersecurity. Fraudsters may impersonate banks, send deceptive payment requests, create fake applications, or manipulate users into sharing confidential information. Businesses and consumers must protect authentication details, verify recipients, use trusted applications, and report suspicious activity promptly.
Regulation is equally important. Financial services involve sensitive personal information and can have serious consequences for customers. Clear rules governing data use, digital lending, payments, and customer complaints help create accountability. FinTech companies must balance innovation with compliance and responsible business practices.
Competition in the sector is also changing. Traditional banks are developing digital services, while technology companies and specialised financial platforms are expanding into selected areas of finance. Partnerships between established institutions and FinTech providers may combine financial expertise with modern technology.
Looking ahead, embedded finance, open banking frameworks, digital identity systems, and improved fraud-prevention tools may further influence how financial services are delivered. Their success will depend on secure implementation and genuine customer value.
The FinTech revolution should ultimately be measured by how effectively it improves people’s financial lives. Faster payments and smarter applications are valuable, but the most meaningful progress occurs when technology makes financial services more accessible, understandable, secure, and responsible.