


Finance is undergoing a transformation driven by digital technology, changing economic conditions, evolving investment opportunities, and a growing recognition that financial resilience matters at every stage of life. Individuals, businesses, and institutions are increasingly expected to make informed decisions in an environment where markets can change quickly and financial products are becoming more accessible through digital platforms.
For individuals, financial planning begins with understanding income, expenditure, savings, and future responsibilities. Although investment opportunities frequently attract attention, financial stability often depends first on managing everyday expenses, preparing for emergencies, and avoiding unsustainable debt. An emergency fund can help households respond to unexpected medical costs, job changes, or essential repairs without immediately relying on expensive borrowing.
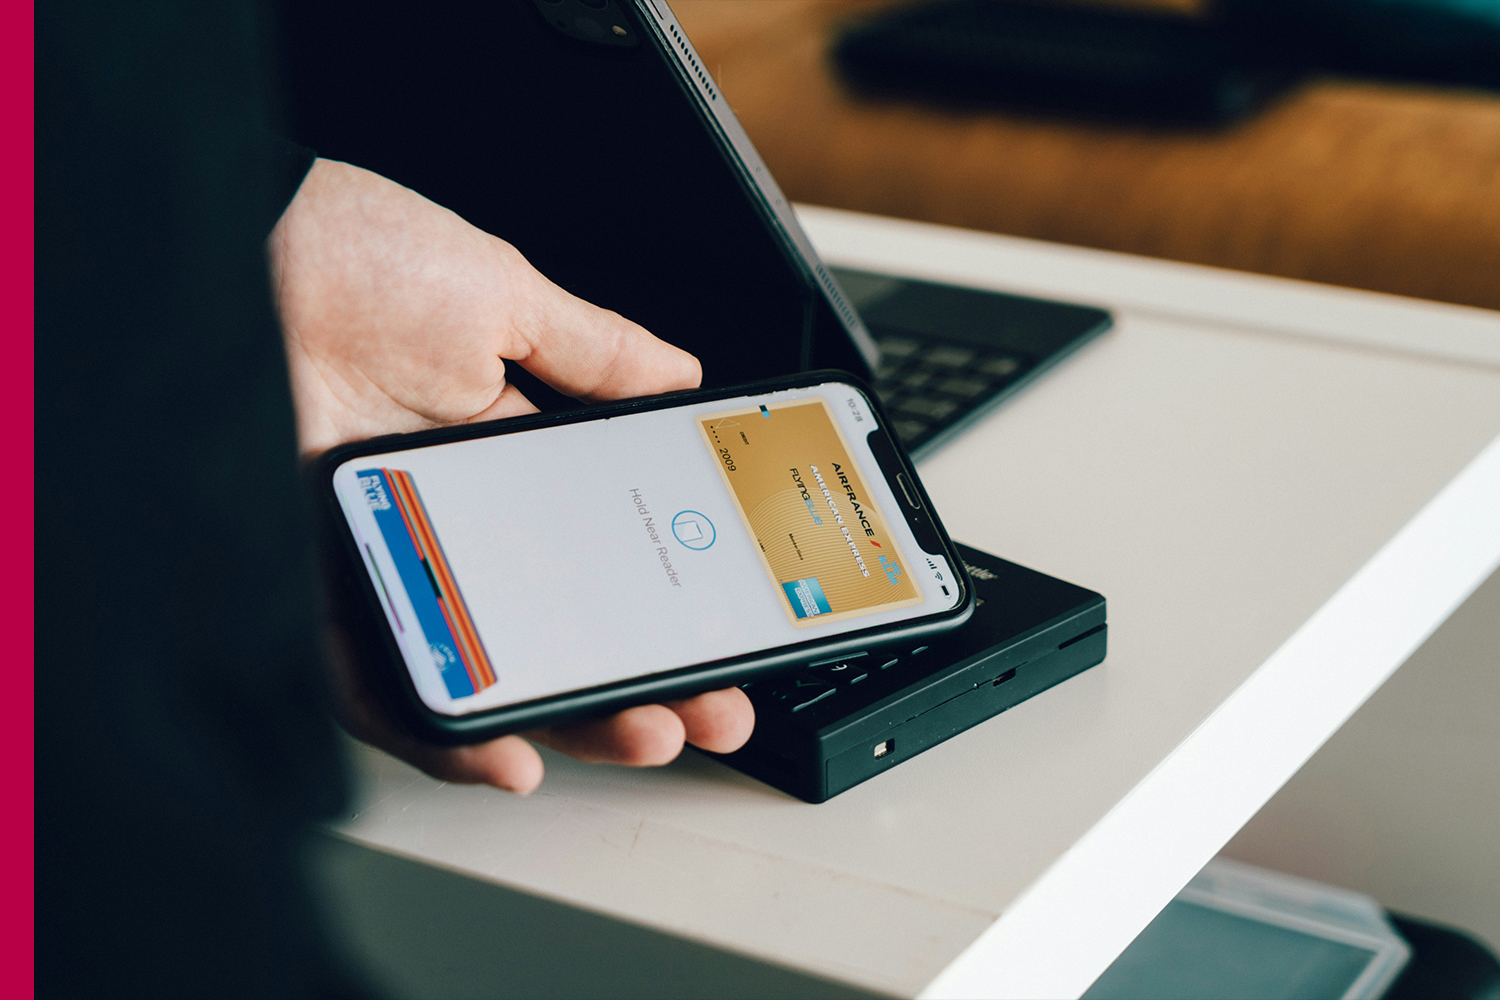
Digital banking has made many financial services more convenient. Customers can transfer money, pay bills, review transactions, and access selected banking services through mobile applications. Digital payment systems have also simplified many everyday transactions. These developments can improve access, but convenience must be accompanied by caution. Fraudulent messages, impersonation, phishing, and unauthorised transactions remain risks that require awareness and appropriate security practices.
Investment decisions are also becoming more individualised. People can explore deposits, bonds, mutual funds, shares, retirement products, and other financial instruments according to their circumstances and risk tolerance. However, greater access to investment platforms does not automatically translate into better decisions. Investors must understand potential losses, fees, liquidity restrictions, tax implications, and the difference between short-term speculation and long-term planning.
Diversification remains an important principle. Concentrating all investments in a single company, sector, or asset class can expose an investor to unnecessary risk. Spreading investments across appropriate categories may reduce dependence on one source of returns, although diversification cannot eliminate losses. The right allocation depends on financial goals, time horizon, income stability, and personal circumstances.
Artificial intelligence and data analytics are changing how financial institutions operate. These tools can support fraud detection, customer service, risk assessment, and the analysis of financial information. Businesses may use predictive analytics to improve cash-flow planning, while banks can use automated systems to identify unusual transactions. Nevertheless, automated decisions require appropriate controls, since inaccurate data or poorly designed models can produce unfair or unreliable outcomes.
For businesses, financial resilience involves more than profitability. Organisations must manage cash flow, monitor expenses, plan for uncertainty, and maintain sufficient resources to meet obligations. A business can generate strong sales yet experience financial difficulties if customers pay late or operating costs rise unexpectedly. Effective financial management therefore connects strategic planning with everyday operational decisions.
Financial inclusion remains another important priority. Access to suitable banking, savings, insurance, and credit products can help individuals and small enterprises participate more fully in economic activity. Yet access alone is not enough. Financial education is necessary to help people understand the responsibilities and risks associated with borrowing, investing, and digital transactions.
In India, digital financial services have expanded opportunities for individuals and businesses to participate in formal financial systems. Continued progress will depend on secure infrastructure, consumer protection, accessible education, and responsible lending practices.
Ultimately, financial success is not simply about accumulating wealth or achieving the highest possible return. It is about building the capacity to manage uncertainty, meet responsibilities, pursue meaningful goals, and make decisions with confidence.
In an unpredictable economic environment, financial resilience comes from preparation, informed judgement, and consistent habits rather than the pursuit of quick gains.